

Planning for long-term care means weighing your assets, your family's goals, and Medicaid's strict rules. A Medicaid Asset Protection Trust (MAPT) is an irrevocable trust that may help you protect certain assets while preparing for potential Medicaid eligibility.
Medicaid rules vary by state, which matters for the families we serve. Arizona runs long-term care Medicaid through AHCCCS and its ALTCS program, while Montana administers it through Montana DPHHS. Our experienced estate planning attorneys are familiar with each state's rules and can help you plan effectively.
What Is a Medicaid Asset Protection Trust (MAPT)?

A Medicaid Asset Protection Trust (MAPT) is an irrevocable trust designed to help individuals qualify for Medicaid benefits while protecting their assets from being counted toward the program's asset limit. By transferring assets into this trust, they are removed from your individual assets for Medicaid eligibility purposes, allowing you to meet the strict financial requirements imposed by the Medicaid program.
These trusts serve as a bridge between protecting your wealth and accessing essential long-term care services when needed. But the asset limits are strict. In 2026, both Arizona and Montana cap countable assets at $2,000 for a single long-term care applicant, with a modestly higher allowance for a married couple, so even a small checking or savings balance can put someone over the asset limit.
How Does a MAPT Work
A MAPT functions by transferring ownership of your assets to an irrevocable trust, making them no longer countable toward Medicaid's asset limit. The trust must be established at least five years before applying for Medicaid benefits to avoid penalties during the look-back period. Neither the grantor nor their spouse can serve as trustee, ensuring the assets are truly beyond the applicant's control for Medicaid purposes.
Important note: The five-year look-back period is critical. Any assets transferred within this timeframe may result in Medicaid ineligibility penalties.
Planning for a MAPT well in advance is essential, because the trustmaker must establish it at least five years before submitting their Medicaid application to avoid violating the program's look-back period rules. This kind of advance planning helps the MAPT do its job without undermining your broader long-term care planning.
What Are the Benefits of a MAPT

Setting up a Medicaid Asset Protection Trust can offer several notable benefits, including the following.
- Asset protection: Shields assets from Medicaid's asset limit and estate recovery programs.
- Preserve family wealth: Protects inheritance for family members and beneficiaries.
- Primary residence protection: Can help safeguard your home from being sold to pay for nursing home care.
- Tax advantages: May reduce estate taxes and provide capital gains tax benefits.
- Planning confidence: Helps families prepare for possible long-term care expenses while preserving eligible assets.
What Are the Shortcomings of a MAPT
While highly useful, MAPTs are not entirely without drawbacks. Here are a few disadvantages worth considering.
- Loss of control: Assets transferred become irrevocable and cannot be easily retrieved.
- Five-year waiting period: Must plan well in advance because of the look-back period requirements.
- High setup costs: Initial legal fees can range from $7,000 to $12,000.
- Income implications: Trust income may affect Medicaid eligibility if it exceeds income limits.
- No automatic approval: A MAPT does not by itself make every applicant eligible for Medicaid.
Can You Protect Your Home with a MAPT
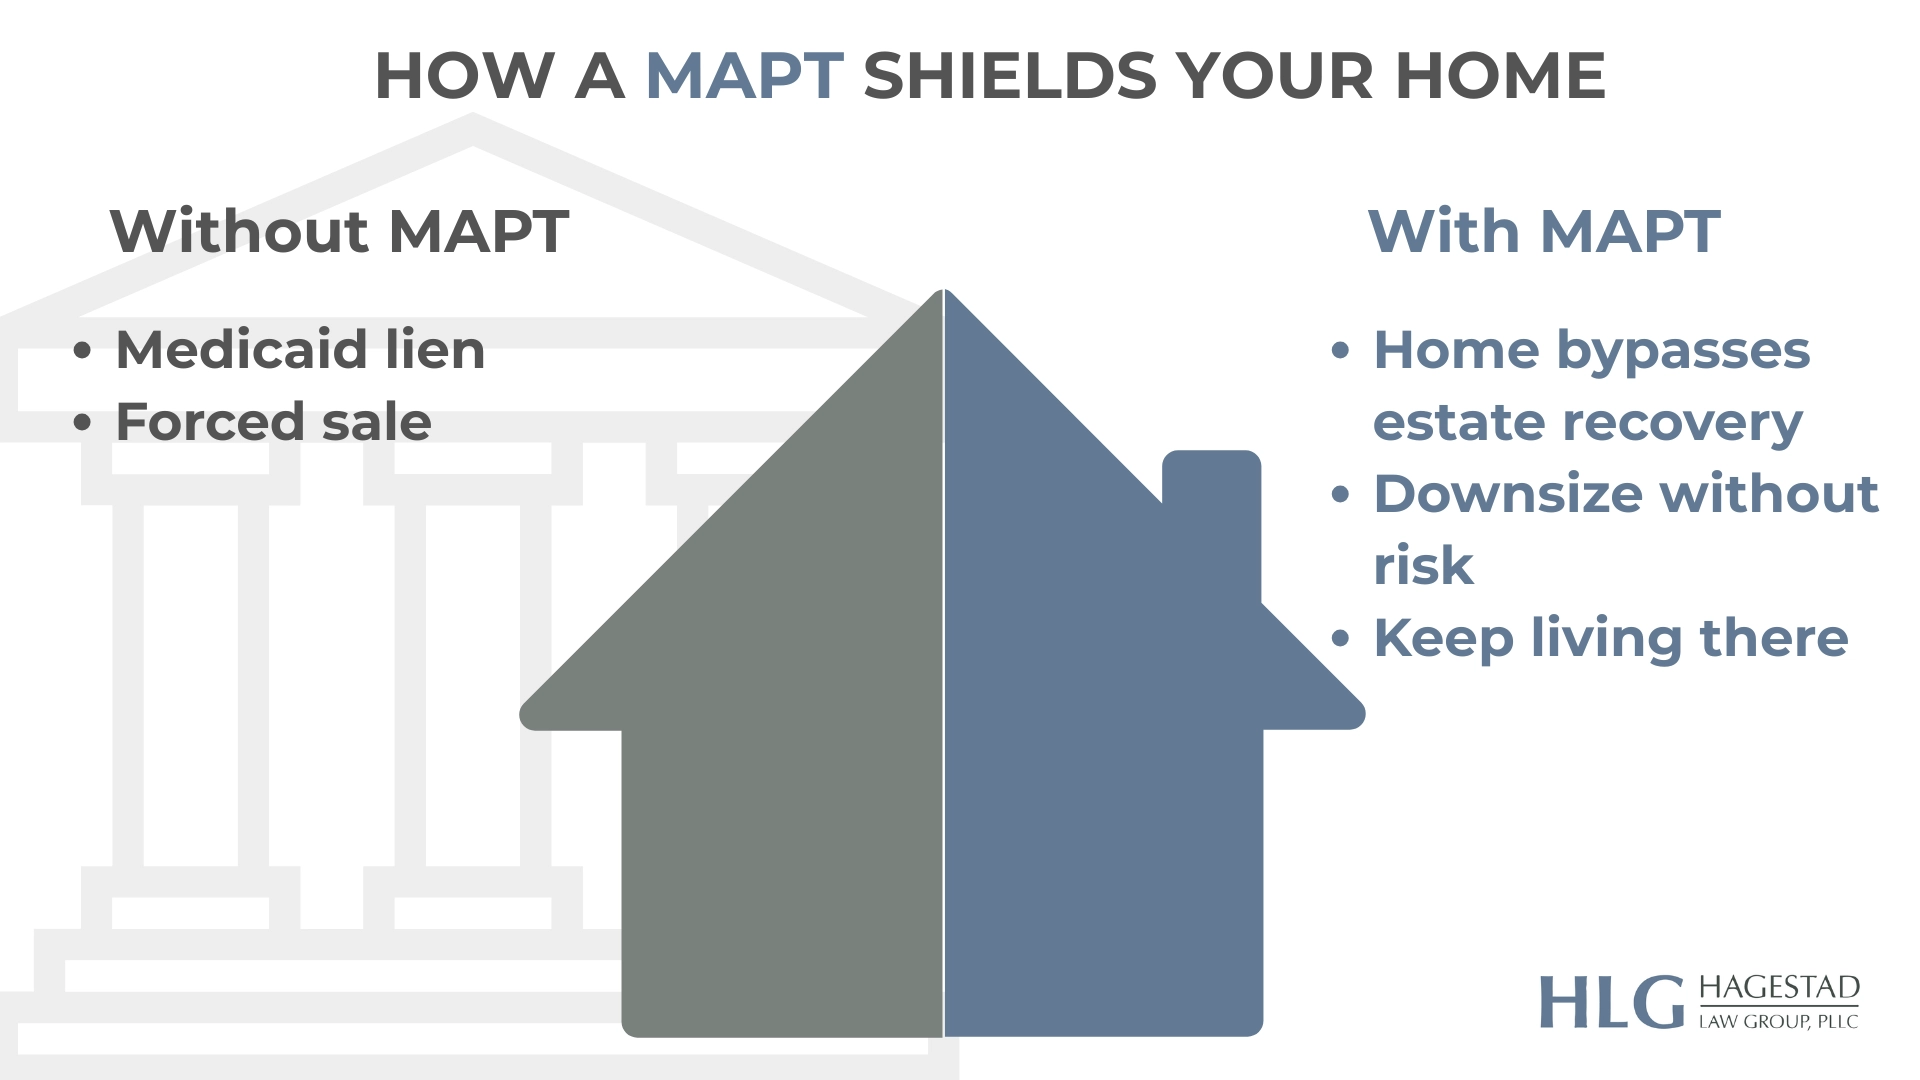
A MAPT may allow certain homeowners to protect their primary residence, depending on individual state laws, trust terms, and Medicaid requirements. Medicaid typically exempts your home from countable assets during the application process, but that exemption does not protect the home from estate recovery after death.
Upon the recipient's passing, state Medicaid agencies commonly seek reimbursement for care expenses by placing liens against the deceased's estate, which may include their family home. Federal rules require states to pursue this estate recovery for people who received long-term care benefits at age 55 or older, and in some cases it can reach property that passes outside probate, such as through an Arizona beneficiary deed. By implementing a MAPT as part of a comprehensive planning strategy, homeowners can reduce this risk.
MAPTs offer flexibility, though, allowing homeowners to downsize to smaller residences while shielding their new properties from Medicaid. Despite the irrevocable nature of MAPTs, certain provisions within the trust structure allow homeowners to retain control over key aspects, such as trustees or beneficiaries.
Can I Sell My Home After Placing It in a MAPT?
Yes. The trustee can sell a home held in the trust, but the proceeds must remain in the MAPT rather than be returned to you directly. A well-drafted trust can also let the trustee buy a replacement residence with those proceeds, so downsizing does not undo the protection.
What Assets Can Be Placed in a MAPT?
Knowing which assets qualify for MAPT protection helps you make informed decisions about your estate planning strategy. Most personal property and financial assets can be transferred, though some retirement accounts require special handling before placement in the trust.
- Bank accounts and savings accounts;
- Investment portfolios and brokerage accounts;
- Real estate properties (including primary residence);
- Certificates of deposit (CDs);
- Stocks, bonds, and mutual funds;
- Business interests and partnerships, especially when they involve family business protection;
- Personal property with significant fair market value;
- Life insurance policies with cash value.
Important note: Certain assets, such as many retirement plans and IRAs, may need to be liquidated before being transferred to a trust.
In some states, transferring one's primary home into a MAPT may not provide complete protection from Medicaid. Even so, MAPTs allow homeowners to continue residing in their homes while benefiting from asset protection strategies. While income-producing assets placed in the trust may generate income, the trustmaker must consider Medicaid's income limit to keep eligibility for benefits. Overall, MAPTs can be a versatile tool for protecting assets and meeting Medicaid eligibility criteria.
How Much Does It Cost to Create a MAPT
Creating a MAPT typically costs between $7,000 and $12,000, depending on several factors, including your location, the attorney's experience, and the value of assets transferred. While this initial investment may seem substantial, the long-term savings often outweigh the upfront expense.
According to the Genworth and CareScout Cost of Care Survey, the national median cost of a private room in a nursing home now exceeds $10,600 per month, or about $127,750 per year. Against numbers like that, a MAPT can be an effective way to help avoid large out-of-pocket long-term care costs, and it costs more than a simpler plan like a revocable living trust in Arizona.
The cost varies based on whether the trust is part of a comprehensive estate planning package, your marital status, and the need for crisis planning. Urban areas generally have higher legal fees than rural locations, and more experienced estate planning attorneys command premium rates for their services.
#cta_start
Secure Your Family's Future with HagEstad Law Group
Work with our dedicated estate planning attorneys at HagEstad Law Group to create a comprehensive strategy that protects your assets and helps you plan for the care you might need later in life.
#cta_end
Is an Attorney Needed to Set Up a MAPT?
Setting up a Medicaid Asset Protection Trust requires meticulous attention to detail to help ensure compliance with Medicaid regulations. Since these regulations frequently change and vary by state, it is important to establish the trust correctly so transferred assets are treated as exempt from Medicaid's asset limits.
Given the potential consequences of errors, families typically rely on an attorney well-versed in MAPT-related laws. Our Arizona estate planning attorneys and Montana trusts and estates team can review your situation and coordinate the trust with the rest of your plan.
Our experienced elder law attorneys will have the knowledge and foresight to handle state-specific requirements, reducing the risk of inadvertently affecting your Medicaid eligibility. Collaborating with a private Medicaid planner who works alongside legal professionals can help streamline the process while keeping costs manageable. This helps avoid the risks of DIY estate planning, which can lead to invalid or ineffective trusts.
What Are Alternatives to a MAPT
Beyond MAPTs, several alternative planning strategies exist to reduce countable assets and qualify for Medicaid, including spend-down methods and other asset protection strategies tailored to individual goals.
Spend-down strategies involve reallocating countable assets into non-countable ones to meet Medicaid's asset limit (for example, home improvements, prepaid burial expenses, or medical equipment). Individuals might also consider irrevocable funeral trusts, which set aside funds for funeral and burial expenses, thereby exempting them from Medicaid eligibility calculations. Another option is Medicaid-compliant annuities, which let individuals convert assets into income streams that comply with Medicaid regulations.
Arizona families have one more tool available. Because Arizona is an income-cap state, applicants whose income exceeds the ALTCS limit often use a Qualified Income Trust, also called a Miller Trust, to meet the income test. Montana instead uses a spend-down pathway, which is one more reason state-specific advice matters.
These alternatives let individuals tailor their estate plans to meet established Medicaid requirements.
What Are the Steps in Creating a MAPT and How Do You Avoid Possible Mistakes
Setting up a Medicaid Asset Protection Trust involves several key steps:
- Consult an experienced attorney: Qualified estate attorneys, such as those at HagEstad Law Group, are essential for handling the procedures involved in forming a MAPT.
- Conduct a comprehensive assessment of your assets: Doing so helps you determine which assets are eligible for transfer into the MAPT.
- Draft a trust document: Your trust document must contain clear terms and trustee responsibilities, along with clearly defined trustee duties and liabilities.
- Fund the trust: Transfer your assets into the MAPT to complete the setup process; this may require changes in titles or beneficiary designations.
To avoid potential pitfalls when establishing a MAPT, you must take care to avoid certain mistakes. One common error is improper funding, which happens when ineligible assets are transferred into the trust, leading to legal and financial complications.
Failing to seek guidance from reliable legal and financial professionals throughout the process can result in Medicaid officials declaring your MAPT invalid, undermining the intended asset protection objectives.
Planning for Long-Term Care with MAPTs
A Medicaid Asset Protection Trust can play an important part in safeguarding your assets while you plan for potential Medicaid eligibility. By establishing a MAPT, you can shield eligible assets from the program's stringent requirements, which can help preserve your legacy for future generations while you plan for the care you may need.
While MAPTs offer numerous benefits, it is important to recognize their potential limitations and consider alternatives when appropriate.
As a law firm serving both Montana and Arizona for years, HagEstad Law Group has extensive experience in Medicaid planning and asset protection strategies for clients facing potential long-term care needs. Contact our office today to discuss how a MAPT might fit into your estate plan and help protect your family's financial security.


